Leave Your Vacation Rental Management to the Experts
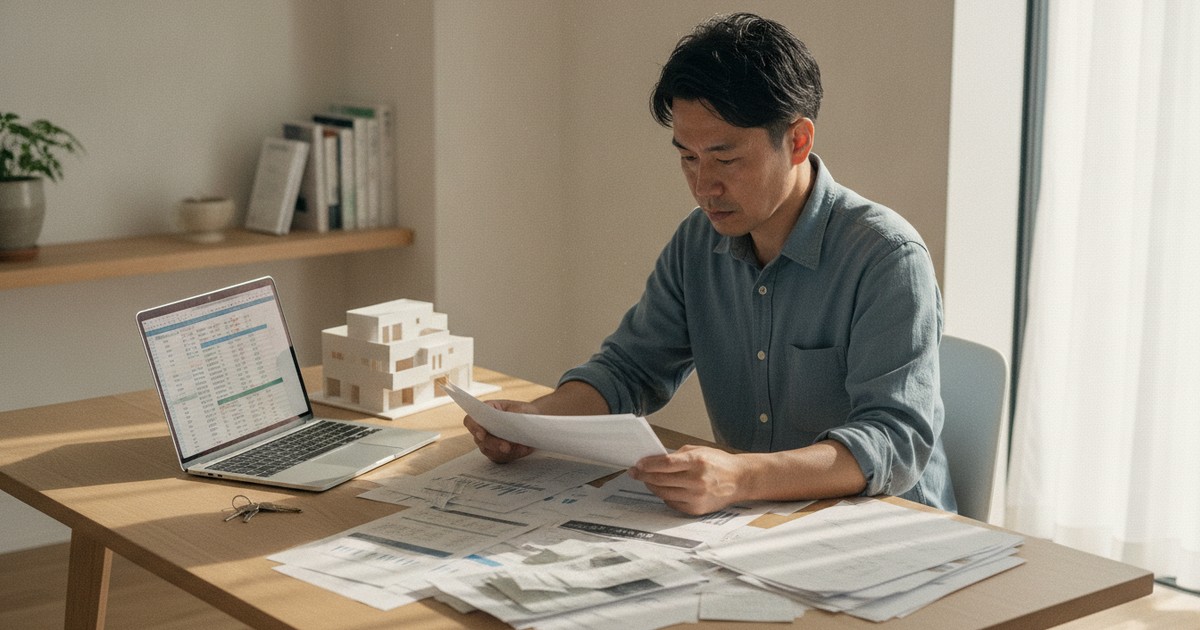
Free Online ConsultationKnowing which costs qualify as a deductible expense against Japan rental property income can materially change your tax position — and for owners living outside Japan, the calculation is complicated by non-resident withholding, JPY remittance timing, and management structures you cannot audit in person. This article works through the main categories from the operator’s side, with the context you need to have an informed conversation with your Japanese accountant.
How Japan Taxes Non-Resident Rental Income
Japan levies income tax on Japanese-source income regardless of where you live. For non-resident owners, a Japanese tenant or paying agent is generally required to withhold 20.42% at source under the Income Tax Act before remitting funds to you. If your management company collects rent on your behalf and remits net proceeds overseas, confirm in writing whether they are fulfilling this withholding obligation — not all operators handle it consistently, and the liability sits with the payer, not with you.
If your annual Japan-source gross income exceeds certain thresholds, or if you elect to file, you submit a kakutei shinkoku (確定申告, annual tax return) by mid-March covering the prior calendar year. Deductible expenses reduce your taxable net income; the difference between getting this right and leaving it generic can run to hundreds of thousands of yen annually on a mid-tier property.
What Actually Qualifies as a Deductible Expense for Japan Rental Property
Japanese tax treatment for rental income follows the National Tax Agency’s guidelines on real property income (fudōsan shotoku). Allowable deductions generally include:
- Management and operation fees — fees paid to a licensed operator or property manager running the property on your behalf. For minpaku and ryokan operations, agency fees (運営代行手数料) typically run in the range of 10–25% of revenue, depending on the scope of work, property type, and level of involvement the company takes on. A full-service operator handling licensing, guest relations, cleaning coordination, and emergency callouts sits toward the higher end; a lighter coordination-only arrangement sits lower. This fee is deductible in full.
- Cleaning and linen costs — direct costs per turnover, including contracted cleaning vendors and laundry services. These are straightforwardly deductible as operating expenses.
- Repair and maintenance — work that restores the property to its original condition qualifies. Capital improvements (upgrades that extend useful life or add value) must generally be capitalised and depreciated rather than expensed immediately.
- Depreciation (genka shōkyaku) — buildings depreciate on a statutory schedule under the Corporation Tax Act and Income Tax Act. Wooden structures typically depreciate over 22 years; reinforced concrete over 47 years. Land does not depreciate. For a non-resident purchasing an older property, the remaining depreciable life — and therefore the annual deduction — can be significant.
- Fixed asset tax (kotei shisan-zei) and city planning tax — billed annually by the municipal government, fully deductible against rental income.
- Insurance premiums — fire and earthquake insurance on the property is deductible. Contents insurance covering guest damage may also qualify depending on how the policy is structured.
- Platform and OTA fees — commissions charged by booking platforms (typically 3–15% of booking value depending on the platform and fee structure) are deductible as the cost of generating income.
- Interest on borrowing — mortgage interest on a loan used to purchase or improve the property is deductible against real property income. Principal repayments are not.
- Licensing and compliance costs — fees paid to obtain or renew a minpaku notification under the Housing Accommodation Business Act, or a ryokan licence under the Hotel Business Act, and fees to a gyōsei shoshi (administrative scrivener) or consultant who manages the application, are deductible.
Consumption tax (JCT, currently 10%) adds a layer of complexity. If your taxable sales exceed ¥10 million in a base period, you become a consumption tax payer and must file separately — at which point input tax credits on deductible expenses become relevant. Most individual owners operating a single property remain below this threshold, but verify with your accountant if you are operating multiple units.
The Cleaning Handover Problem — and Why It Affects Your Tax Records
Here is something that comes up operationally and has a direct bearing on whether expenses hold up under scrutiny. We coordinate cleaning vendors for properties across multiple prefectures. In practice, many small cleaning contractors — particularly in regional areas — prefer to invoice irregularly, issue handwritten receipts, or bill in lump sums covering multiple turnovers without itemisation. When a tax investigation (zeimu chōsa) or even a routine accountant review asks for documentation, a stack of undated handwritten memos does not constitute adequate evidence of a business expense.
We resolved this by requiring all vendors to issue itemised ryōshūsho (領収書, official receipts) per visit or per monthly summary, with the property address, date, and service described. It takes one firm conversation to set the expectation. The broader point for overseas owners: your deduction is only as strong as your documentation, and you are not there to chase paperwork. Build the requirement into any contract you sign with an operator — ask them explicitly how cleaning and maintenance costs are documented and how records are shared with your accountant.
Licensing Structure Determines Which Expenses Are Relevant
The operating licence you hold shapes both your income ceiling and your deductible cost profile.
Under the Housing Accommodation Business Act (Minpaku Law, commonly called the 180-day law), annual hosting is capped at 180 nights nationally, with many municipalities imposing shorter windows. Some wards in Kyoto restrict operation to specific months; Tokyo’s special ward rules vary by district. The practical effect is that your gross revenue is structurally limited, which makes cost management more critical — there is no volume to absorb inefficiency.
A ryokan business licence under the Hotel Business Act removes the 180-day cap entirely and allows year-round operation. The licensing process is more demanding — fire safety compliance under the Fire Service Act, a front desk requirement (which can sometimes be met remotely with regulatory approval), building use change approval — but the operating economics are different and the deductible cost base is typically larger.
Regarding national strategic special zones (tokku minpaku): as of 29 May 2026, Osaka City has permanently closed new applications for tokku minpaku certification. Existing certified facilities may continue, but anyone looking to open a new property in Osaka cannot use this route. New openings in Osaka should be structured under either the Minpaku Law or the ryokan licence. Other designated zones — some areas of Tokyo, Fukuoka, Niigata, and others — retain their own rules, which differ from one zone to the next. Never assume one zone’s conditions apply to another.
What Overseas Owners Often Miss
Several deductions are routinely under-claimed by non-residents who are not close enough to the operation to know they exist.
Travel to Japan specifically to inspect or manage the property can be partially deductible against rental income where the primary purpose is business — though the allocation between personal and business portions requires care and documentation. This is worth discussing with your accountant before booking, not after.
Professional fees paid to a Japanese tax accountant (zeirishi) or to your operator for filing-related support are deductible. Translation costs for documents used in managing the property may also qualify. If you are paying a gyōsei shoshi annually to maintain your minpaku notification or handle municipal reporting, that fee is deductible.
Foreign exchange losses are not deductible against Japanese rental income — Japan taxes the yen amount received or accrued, and currency conversion costs are treated as a personal matter for non-resident owners. This is a common point of confusion when owners receive JPY proceeds that have weakened against their home currency by the time of remittance.
Working With Your Accountant From Overseas
A Japanese zeirishi (registered tax accountant) is the appropriate professional for your annual filing. Your operator should be able to provide them with a clean income and expense summary — broken down by category, with supporting documentation attached — covering the Japanese fiscal year (January to December). If your operator cannot produce this without significant chasing, that is a structural problem in how they run their books, not an administrative inconvenience.
Questions worth asking your operator before you sign a management agreement: How do you document cleaning and maintenance costs? Do you issue a monthly owner report with itemised expenses? Can your records be shared directly with my Japanese accountant? How do you handle the withholding obligation on remittances to non-residents? The answers tell you a great deal about whether they are built for overseas ownership or simply accustomed to domestic clients who can walk in and ask.
Stay Buddy manages minpaku and ryokan operations end-to-end on behalf of overseas owners. If you want to understand the operating structure for a specific property before committing, contact us directly — we will give you a straight answer based on what we actually see in the market.
Leave Your Vacation Rental Management to the Experts
Free Online ConsultationShuhei Makigi
Representative Director, Stay Buddy Co., Ltd.
Registered Housing Accommodation Management Business — Ministry of Land, Infrastructure, Transport and Tourism No. F03862. Stay Buddy operates short-term rentals and licensed hotels across Japan, supporting overseas investors with compliant, high-performing properties.
Written by the Stay Buddy Japan team. This content was produced with AI assistance and reviewed for accuracy.