Leave Your Vacation Rental Management to the Experts
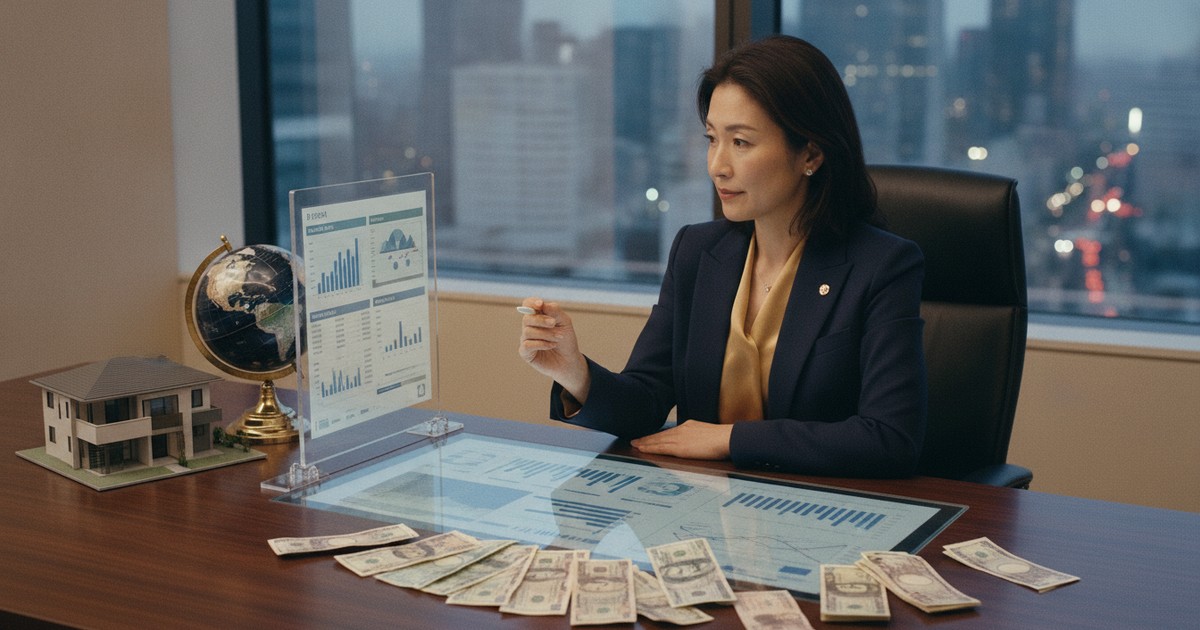
Free Online ConsultationOwning rental property in Japan while living abroad means your income arrives in yen, your mortgage or lifestyle costs sit in another currency, and the gap between those two realities is where currency risk in Japan rental income quietly erodes returns that look perfectly healthy on a yen-denominated spreadsheet. This isn’t a peripheral concern — over the past few years the yen has swung from the low 100s to above 155 against the dollar and sterling, a range wide enough to change whether a property is profitable in your home currency at all.
Why Japan Rental Income Currency Risk Hits Non-Residents Harder
A domestic Japanese owner spends in yen, so exchange rate movement is largely irrelevant to them. You do not have that buffer. Every time we remit net proceeds to an overseas owner — after management fees, cleaning costs, repair reserves, and applicable taxes — the yen amount that leaves our account becomes something different by the time it arrives in their bank. If the yen weakens 10% over a quarter, that is effectively a 10% rent cut on top of any vacancy.
The compounding effect matters too. Management fees for a minpaku or ryokan operation typically run somewhere between 10% and 25% of gross revenue, depending on the scope of services, property type, location, and what the management company actually handles end-to-end. Cleaning, linen, maintenance coordination, guest communication, licensing compliance — each scope addition sits toward the higher end of that range. Once fees and local costs are deducted, the net figure remitted is smaller, which means foreign exchange losses apply to an already-compressed margin.
The Yen Payout Cycle and Where Slippage Occurs
In a typical short-term rental operation in Japan, booking revenue collects across platforms — OTAs such as Airbnb, Rakuten Travel, Jalan — each with their own payout timing, sometimes 24 hours post-checkout, sometimes monthly in arrears. We consolidate those receipts, deduct operating costs, apply any withholding obligations, and remit to the owner, usually monthly. That cycle means there is always a lag between a guest paying in yen and the owner receiving a converted amount in their home currency. Rates on the day of remittance govern the conversion, not the rate when the booking was made.
Wire transfer fees add another layer. Depending on the sending bank and the receiving country, international transfers typically cost somewhere between ¥2,000 and ¥5,000 per transfer on the Japanese side, plus whatever the receiving bank charges. For owners receiving modest monthly payouts — particularly during low-occupancy months under a standard minpaku licence, which caps operating days at 180 per year under the Housing Accommodation Business Act — fixed transfer fees consume a disproportionate share of a small remittance. We often recommend quarterly consolidation for properties where net monthly income regularly falls below a threshold the owner and we agree in advance.
What We Actually Do When a Payout Decision Has to Be Made Under Pressure
Last winter, we had a situation at a machiya property in Kyoto where a neighbour complaint about noise — a recurring risk in densely built residential areas — required us to commission emergency acoustic assessment and install additional soundproofing. The cost came to roughly ¥280,000. The owner’s reserve fund held in Japan covered part of it, but not all. The timing coincided with the yen sitting near multi-decade lows.
The owner wanted to wire funds from abroad to top up the reserve. We had a direct conversation about whether to send immediately or wait. We do not offer financial advice, and we are not currency brokers — we said that clearly — but we walked through the operational reality: the contractor needed payment within ten days, the permit amendment related to the noise complaint had a filing deadline, and holding out for a better rate carried a real operational risk, not just a financial one. The owner transferred at a rate that, in retrospect, was not the worst of the month. The point is that currency timing decisions in a Japan rental operation rarely happen in isolation from compliance deadlines, contractor availability, or neighbour relations. They happen under pressure.
Tax Obligations That Affect What Actually Gets Remitted
Non-resident owners of Japanese property face obligations that domestic owners do not, and these directly affect net remittances. Under Japanese tax law, non-residents are subject to withholding tax on rental income sourced in Japan. The standard withholding rate under domestic rules is 20.42%, though the effective rate on net income after allowable deductions — depreciation, management fees, insurance, property tax — can differ significantly. A tax treaty between Japan and the owner’s country of residence may reduce or restructure this liability; the Japan National Tax Agency publishes applicable treaty rates by country.
Owners are generally required to appoint a tax agent (納税管理人) resident in Japan to file on their behalf. This is not optional formality — failing to appoint one can result in the local tax office treating gross receipts, not net income, as the taxable base. We help connect owners with qualified tax agents but we are not a tax firm; the owner’s filing obligation is their own.
Consumption tax (消費税) applies once taxable sales exceed ¥10 million in a base period, a threshold most individual short-term rental properties do not reach, but portfolio owners or those operating under a ryokan licence across multiple units should verify with their tax agent whether registration is required.
Licensing Structure and How It Affects Income Predictability
Income predictability is part of currency risk management — you cannot hedge what you cannot forecast. The licensing framework in Japan creates meaningful differences in revenue ceiling and consistency.
Under the Housing Accommodation Business Act (Minpaku Law), standard minpaku properties are capped at 180 operating days per year nationally, with municipalities frequently imposing further restrictions by zone or season. Some Tokyo wards, for instance, restrict operation to specific day-of-week periods. The resulting income is structurally intermittent, which complicates any hedging or forward planning.
A ryokan business licence under the Hotel Business Act removes the day cap and permits year-round operation, but requires facility compliance with the Fire Service Act (消防法) — sprinklers, fire doors, emergency lighting — and ongoing inspection obligations. This path suits properties that can genuinely be brought to hotel-grade specification.
The national strategic special zone framework (tokku minpaku, 国家戦略特区) previously allowed certain municipalities to operate beyond the 180-day cap. Osaka City operated a significant tokku minpaku scheme, but as of 29 May 2026, Osaka City has permanently closed applications for new tokku minpaku certification. Existing certified operators may continue, but no new tokku minpaku facility can be started in Osaka. Owners considering a new opening in Osaka must pursue either the standard Minpaku Law route or a full ryokan licence. Verify the current position with the relevant municipal office before making any purchase decision.
Practical Steps for Managing Currency Exposure
We cannot manage your foreign exchange position for you, but we can structure the operational side to give you better information and more control over timing.
- Maintain a yen reserve fund in Japan. We recommend holding three to four months of estimated operating costs locally. This reduces forced remittances during rate troughs and covers emergency spend — like that Kyoto acoustic job — without requiring an international wire under time pressure.
- Agree remittance frequency and minimum thresholds upfront. Monthly remittances of small amounts amplify transfer costs and leave no room to choose timing. Quarterly with a minimum floor gives more flexibility.
- Ask your management company for itemised monthly reporting in yen. If you only receive converted figures, you cannot distinguish a bad exchange month from a bad occupancy month. Insist on yen-denominated revenue and cost reporting, separately from any conversion your management company applies.
- Consider a multi-currency account or FX service. Services such as Wise Business, or currency brokers who offer forward contracts, allow you to receive yen and convert at a time you choose, or lock in a rate for a defined period. These are not guarantees against loss but they do separate the operational timing from the conversion timing.
- Understand what your management fee covers before signing. A fee quoted toward the lower end of the 10–25% industry range may exclude guest communication, maintenance coordination, or compliance monitoring — all of which create unpredictable out-of-pocket costs that affect your net remittable income in ways you cannot plan for.
If you are evaluating a Japan short-term rental purchase from abroad and want to understand what realistic net-remittable returns look like under current licensing, tax, and operational conditions for a specific property type or location, we are glad to work through the numbers with you based on what we actually see running these properties.
Leave Your Vacation Rental Management to the Experts
Free Online ConsultationShuhei Makigi
Representative Director, Stay Buddy Co., Ltd.
Registered Housing Accommodation Management Business — Ministry of Land, Infrastructure, Transport and Tourism No. F03862. Stay Buddy operates short-term rentals and licensed hotels across Japan, supporting overseas investors with compliant, high-performing properties.
Written by the Stay Buddy Japan team. This content was produced with AI assistance and reviewed for accuracy.