Leave Your Minpaku Management to the Experts
100% Free Online ConsultationBefore Filing Your Minpaku Tax Return, Start by Confirming Your Income Classification
To make sure you claim every eligible expense on your minpaku tax return, the first step is confirming whether your income falls under “miscellaneous income” or “business income.” This classification determines whether you can apply the special blue-form tax deduction, and the difference can add up to hundreds of thousands of yen in what you actually keep. Having supported the operations of numerous property owners, Stay Buddy has seen no shortage of cases where hosts, in their first year of filing, discover they’ve missed deductible expenses or misclassified their income type.
Miscellaneous Income or Business Income: Which Applies to Minpaku?
Whether your property is registered under the Private Lodging Business Act (commonly known as the “minpaku law”) or licensed under the Hotel Business Act, your income classification is determined by the scale, continuity, and profit-seeking nature of your operation. Under National Tax Agency guidelines, if your activity is recognized—by common social standards—as having the scale and substance of a genuine “business,” it’s treated as business income; otherwise, it’s classified as miscellaneous income.
The Private Lodging Business Act caps annual operating days at 180, and hosts running just one or two rooms as a side activity tend to be classified under miscellaneous income. On the other hand, operators licensed under the Hotel Business Act who run multiple rooms year-round are more likely to qualify for business income status. That said, this determination depends heavily on individual circumstances, so if you’re unsure, we strongly recommend checking with your local tax office or a licensed tax accountant.
What Changes If You Qualify for Business Income Status
If your business income is approved for blue-form filing, you can claim a special deduction of up to ¥650,000 (conditional on e-Tax filing and double-entry bookkeeping). You’ll also be able to carry forward net losses for up to three years and pay salaries to family members working in the business as “blue-form business-dedicated employees,” which can also be deducted. Miscellaneous income doesn’t allow loss carry-forwards, so the tax treatment differs significantly in years when renovations or equipment investments push you into the red.
A List of Deductible Expenses for Minpaku Tax Returns
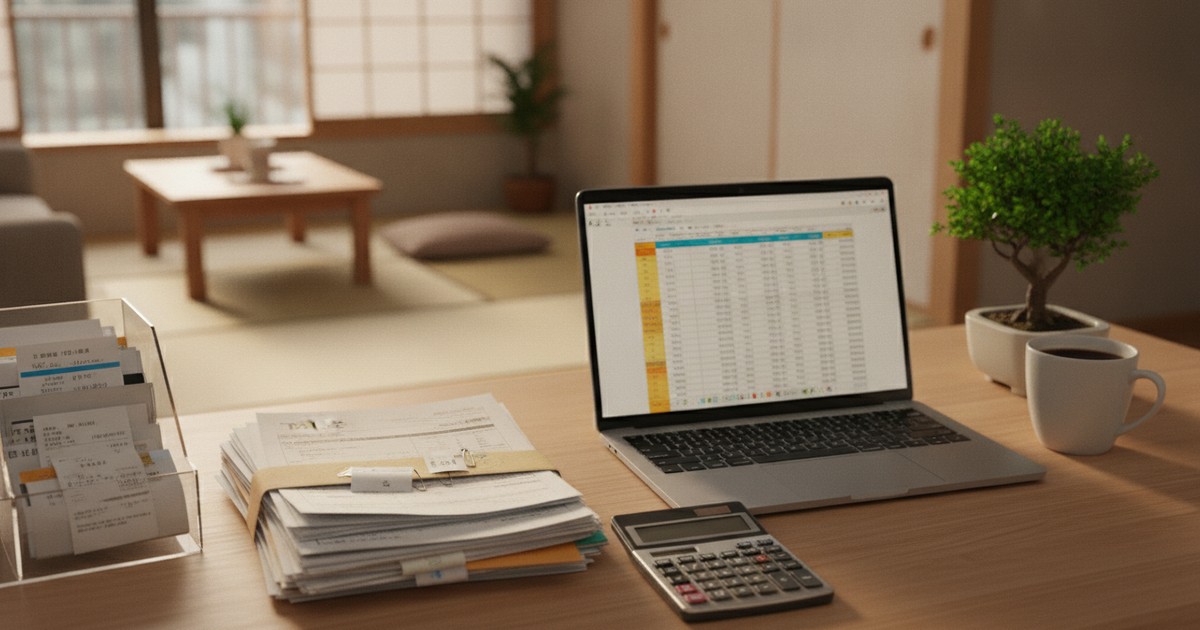
Below are expense categories commonly recognized as deductible in minpaku operations. In every case, the underlying requirement is the same: the expense must be directly related to your business, and you must have receipts or statements proving the payment actually occurred.
Cleaning and Maintenance Costs
Cleaning costs incurred after guest checkout can be claimed as expenses, whether outsourced or handled yourself. In Stay Buddy’s field operations, we’ve seen cases where a string of last-minute cancellations forced a rescheduling of cleaning, resulting in premium fees for emergency spot-cleaning services. As long as such unplanned costs arise from business operations, they can be claimed as expenses—the same goes for repair and replacement costs for fixtures and equipment.
Management Agency Fees and Administrative Commissions
Fees paid to a property management company, as well as commissions charged by OTA platforms (Airbnb, Booking.com, etc.), can be claimed in full as expenses. OTA commission rates for hosts generally range from around 3% to 20%, though this varies depending on the platform and pricing model used.
Depreciation
Appliances, furniture, and equipment purchased for your minpaku property that cost ¥100,000 or more generally must be depreciated over their useful life. However, blue-form filers can take advantage of a special provision (Article 28-2 of the Act on Special Measures Concerning Taxation) that allows immediate full expensing of low-value depreciable assets under ¥300,000, up to a combined annual limit of ¥3 million. If you own the building used for your minpaku operation, you can also claim depreciation on the building itself, proportional to the share used for minpaku purposes.
Utilities and Communication Costs
If you’re using part of your own home for minpaku, you can’t deduct these costs in full. Instead, you need to apportion them based on factors like the floor area used for minpaku or the number of days it was in operation. Be sure to keep records documenting the basis for your apportionment.
Supplies and Amenities
Towels, sheets, toilet paper, shampoo, and other guest amenities all qualify as deductible expenses. Small furniture items and kitchen tools costing under ¥100,000 can also be expensed in full as consumable supplies.
Insurance Premiums
Premiums for liability insurance specifically covering minpaku operations, or facility liability insurance required under the Hotel Business Act, can be claimed as expenses. Fire insurance premiums can also be partially deducted, apportioned to reflect the share related to your minpaku business.
Licensing and Registration Costs
Fees paid to administrative scriveners (gyoseishoshi) and application fees for registering under the Private Lodging Business Act or obtaining a license under the Hotel Business Act are also deductible. Costs for installing fire safety equipment required under the Fire Service Act (such as automatic fire alarms and emergency exit lights) may be expensed immediately or depreciated, depending on the amount.
What Doesn’t Count as an Expense—and How to Handle Gray Areas
Expenses that serve both personal and business purposes—such as rent or parking fees for your own residence—cannot be claimed in full. You’ll need to calculate a reasonable business-use percentage and apportion accordingly. The same applies to travel expenses: if a trip combines personal travel with business purposes like inspecting a minpaku property, only the business-related portion can be claimed.
Rather than simply avoiding any expense you’re unsure about, the more accurate approach is to prepare documentation that clearly explains its connection to your business. Keeping records such as calendar entries, photos, and email exchanges with vendors will make it much easier to justify your apportionment calculations if you’re ever subject to a tax audit.
Record-Keeping Periods and the Tax Filing Process
For blue-form filers, ledgers, receipts, contracts, and other documentation must generally be kept for seven years (since tax audits under Article 74-2 of the Act on General Rules for National Taxes can cover up to seven years). White-form filers are required to retain records for five years. The deadline for filing your tax return is March 15 of the following year, and applications to be approved for blue-form filing must generally be submitted by March 15 of the year you start operations (or within two months of starting, if you begin after January 16).
For Property Owners Struggling With Minpaku Tax Filing and Expense Management
Stay Buddy Co., Ltd. provides comprehensive support for minpaku and hotel business operations—from license and registration applications through day-to-day management and financial reporting. We’re also happy to advise on organizing the expense records you’ll need for tax filing and on building a solid working relationship with a tax accountant.
Even if you’re starting from square one—unsure whether your property counts as miscellaneous or business income, or unclear on how to apportion which expenses—we can give you concrete answers. We provide practical advice tailored to your property’s scale, operating style, and location.
During your first free consultation, we’ll ask about your current operations and walk you through the expense categories most commonly overlooked in tax filings, along with recommended bookkeeping practices. Feel free to reach out—we’d be glad to help.