Leave Your Vacation Rental Management to the Experts
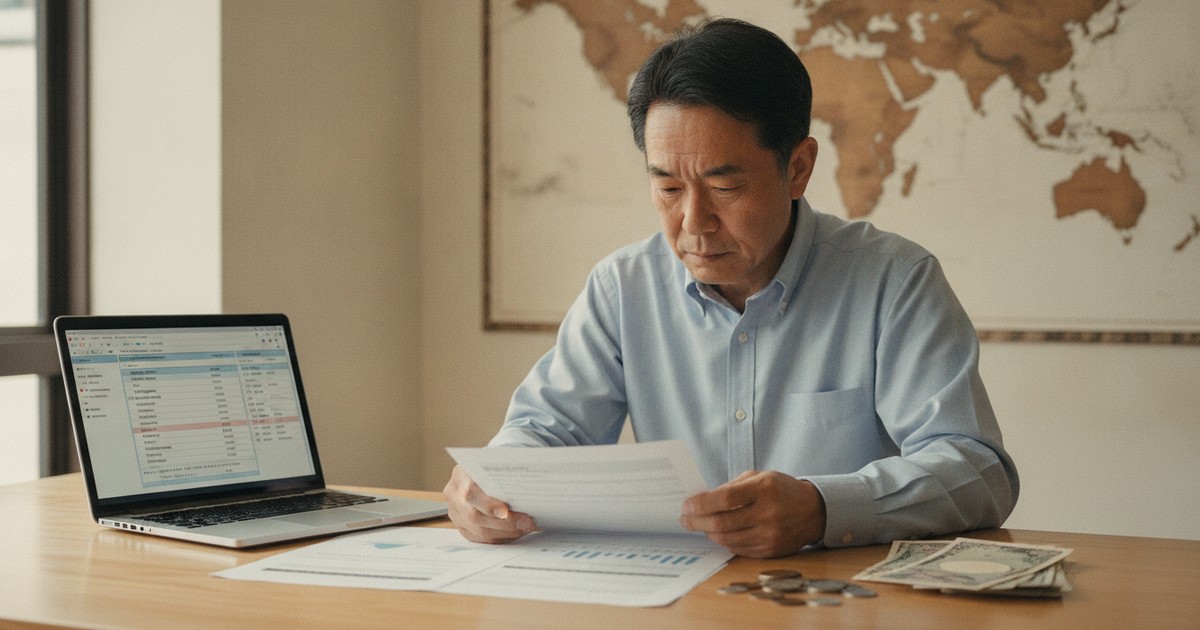
Free Online ConsultationIf you own a short-term rental in Japan and live abroad, you face a problem most property guides skip entirely: after the bookings come in, the taxes are settled and the management fees are deducted, how do you actually get your money out of Japan — and does it arrive in a form that makes sense? For any international remittance Japan landlord arrangement to work cleanly, you need to understand the Japanese tax obligations that touch the payment before it leaves, the banking rails that carry it, and the currency risk that erodes it before it hits your account. This guide covers all three, from the point of view of someone who runs these properties on the ground.
What the Japanese Tax System Does to a Non-Resident Landlord’s Income First
Before any remittance conversation begins, non-resident owners need to understand that Japan taxes income arising on Japanese soil regardless of where you live. Under the Income Tax Act, rental income — including minpaku and ryokan income — paid to a non-resident is subject to withholding tax at source. The standard rate for rental income paid to non-residents is typically 20.42% (20% plus the 2.1%復興特別所得税 reconstruction surtax, in effect until 2037), applied to gross rental receipts before expenses.
This withholding obligation falls on whoever pays the income to you. If your management company collects guest revenue and remits it to you overseas, they are technically the payer and may be required to withhold and file on your behalf. Many operators — ourselves included — structure payments through a Japanese bank account held in the owner’s name precisely to manage this cleanly. A non-resident can open a Japanese bank account; it requires a valid residence card or, in some cases, a Japanese representative. Your tax agent (税理士) should be filing an annual non-resident tax return to reconcile withholding against actual allowable deductions, which can reduce your effective rate considerably.
Consumption tax (消費税) is a separate matter. If your annual taxable sales in Japan exceed ¥10 million, you become a consumption tax registrant. Most individual property owners operating a single minpaku or small ryokan fall well below this threshold, but group investors or those with multiple properties should verify with their 税理士.
Licensing Reality: Minpaku Law, Ryokan Licence and What’s Actually Available to You
The structure of your operation determines your revenue profile, which determines what you’re remitting. Under the Housing Accommodation Business Act (the Minpaku Law, 2018), standard minpaku are capped at 180 operating days per year nationally. Municipalities can — and frequently do — impose tighter restrictions by zone or by day of week. This ceiling directly limits annual revenue.
The alternative is a full ryokan business licence under the Hotel Business Act, which carries no day-cap but requires structural compliance with fire prevention standards under the Fire Service Act, a responsible manager registered at the facility, and front-desk provisions. Licensing costs and timelines vary significantly by prefecture and property age.
A note specifically on Osaka: the city previously offered an accelerated pathway under national strategic special zone (tokku minpaku) rules, which permitted longer operating periods. As of 29 May 2026, Osaka City has permanently closed new applications for tokku minpaku certification. Existing certified facilities may continue, but there is no route for new applicants in Osaka under the tokku framework. New Osaka properties must pursue either the standard Minpaku Law registration or a ryokan licence.
Management Fees, Transparency and the Operator You’ll Never Meet in Person
This is where non-resident ownership either works or quietly falls apart. Operator fees for running short-term rentals in Japan — covering guest communication, check-in, cleaning coordination, compliance filing and revenue management — typically range from 10% to 25% of gross revenue, depending on the scope of services, property type, location, and operator. A company handling only booking management at the lower end looks very different from one covering licence maintenance, neighbour liaison, linen logistics and local tax liaison at the higher end. Never accept a fee quote without a clear written scope attached to it.
Here is a specific example of why that matters. We manage a machiya townhouse in Kyoto for an owner based in Germany. During one winter period, our regular cleaning vendor had a staffing shortage — common in Japan’s tight hospitality labour market in peak season — and we had a same-day turnover between a five-night checkout and a two-night check-in. We made the call to bring in a backup cleaning team we’d qualified the previous autumn, accepted a higher per-clean cost, and held the check-in time. The owner saw a slightly higher cleaning expense line that month. When she queried it, we sent the vendor invoice, the original team’s cancellation notice and the check-in log. That kind of paper trail — provided without being asked — is what separates an operator from a middleman. When vetting any management company remotely, ask specifically: what do you do when your primary vendor fails on a same-day turnover, and how do you document it for the owner? The answer tells you more than any brochure.
Other questions worth putting to any prospective operator: How is revenue reported — gross or net, and at what frequency? Do you hold owner funds in a segregated client account? Who files the non-resident withholding? Can you provide the name and registration number of your 管理業務主任者 or responsible manager?
International Remittance Japan Landlord Options: Moving the Money Efficiently
Once revenue clears Japanese tax obligations and management deductions, you need to move it. Your main options, with their practical trade-offs:
- Japanese domestic bank wire (telegraphic transfer): Reliable, with full audit trail. International wires from major Japanese banks (Japan Post Bank, MUFG, SMBC, etc.) typically carry transfer fees in the range of ¥2,500–¥4,000 per transaction plus a correspondent bank charge at the receiving end. Exchange rates applied by Japanese banks can be 1–2% or more away from mid-market. Suitable for larger quarterly remittances where the fixed fee is proportionally small.
- Wise (formerly TransferWise): Widely used by non-resident owners for JPY-to-foreign-currency transfers. Wise applies rates close to mid-market and charges percentage-based fees that are typically lower than bank spreads on smaller amounts. It requires a verified Japanese bank account as the sending account. Not a bank — confirm your own country’s regulatory treatment for tax reporting.
- PayPal and similar platforms: Higher conversion costs and less transparency on the FX spread. Generally not recommended for regular landlord remittance flows.
- Batch remittance via your operator: Some operators remit net proceeds directly to your overseas account after deducting fees and withheld tax. Simpler operationally, but you lose visibility on the gross-to-net calculation. Always request a detailed remittance statement, not just the net deposit.
Currency timing matters. JPY has experienced significant volatility in recent years. Whether you remit monthly, quarterly or annually is partly a cash-flow decision and partly a currency view. There is no universally correct answer; what matters is that you make it deliberately rather than by default.
Bank Accounts, Reporting and the Non-Resident Paper Trail
Japan does not require non-resident property owners to hold a local bank account, but having one substantially simplifies operations — utility direct debits, tax payments, management fee settlement and remittance origination all become cleaner. Opening a Japanese account as a non-resident is possible at some institutions (Japan Post Bank has historically been more accessible, though policies vary by branch and change over time); it generally requires a resident proxy or a visit to Japan. Some owners use a trusted local representative or their management company’s nominee account, which introduces its own risks and should be covered by a written agency agreement.
For FATCA (US persons) and CRS (most other nationalities) reporting purposes, a Japanese bank account is a reportable foreign financial account. Confirm your home-country disclosure obligations with a tax adviser before opening one.
The Japan Tourism Agency maintains registration databases for minpaku operators; your property’s registration number should appear there. Non-resident owners should keep copies of their licence or registration, annual tax return filings, and remittance records. Japanese tax statute of limitations for reassessment is generally five years for ordinary cases, seven for fraud — keep documentation accordingly.
Working With Stay Buddy as a Non-Resident Owner
We operate properties, not just manage them. That means when something breaks — a licensing query from the ward office, a neighbour complaint about noise at 23:00, a cleaning handover that nearly went wrong — we handle it and document it, rather than forwarding it to you and waiting. Non-resident owners working with us receive a monthly revenue and expense report, a remittance statement showing gross, withheld tax, fees and net, and direct access to our operations team when a decision requires owner input. If you’re evaluating whether your current Japanese property — or a property you’re considering — can generate a viable remittance yield after tax, fees and currency friction, we’re willing to work through the numbers with you before any commitment is made.
Leave Your Vacation Rental Management to the Experts
Free Online ConsultationShuhei Makigi
Representative Director, Stay Buddy Co., Ltd.
Registered Housing Accommodation Management Business — Ministry of Land, Infrastructure, Transport and Tourism No. F03862. Stay Buddy operates short-term rentals and licensed hotels across Japan, supporting overseas investors with compliant, high-performing properties.
Written by the Stay Buddy Japan team. This content was produced with AI assistance and reviewed for accuracy.